| Summary
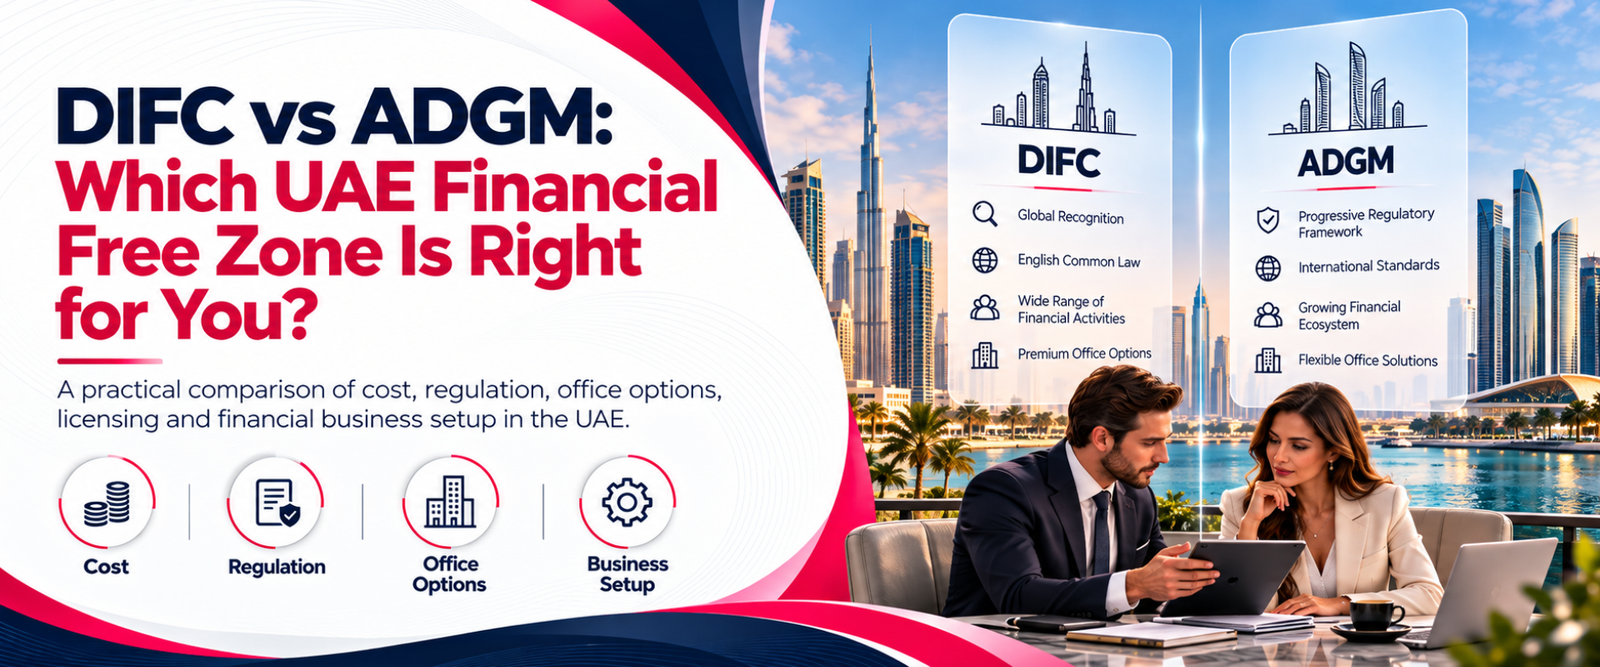
DIFC and ADGM are the UAE’s two premier financial free zones, both governed by English common law with independent courts and world-class regulators. DIFC sits in Dubai and hosts over 350 financial institutions; ADGM operates from Al Maryah Island in Abu Dhabi with a RegLab fintech sandbox. This guide covers legal frameworks, regulators, costs, and the key differences that should drive your choice. |
Quick Facts: DIFC and ADGM Side by Side
| Factor | DIFC | ADGM | Verdict |
| Location | Dubai | Abu Dhabi | Depends on emirate |
| Legal framework | DIFC Law (Common Law) | ADGM Law (Common Law) | Both English common law |
| Regulator | DFSA | FSRA | Both world-class |
| Financial institutions | 350+ | Growing rapidly | DIFC by volume |
| Fintech sandbox | FinTech Hive | RegLab | ADGM for regulatory sandbox |
| Foundations / trusts | Good support | Slight legal edge | ADGM for trusts/foundations |
| Cost (approx.) | USD 8,000–15,000+ | USD 7,000–13,000+ | ADGM marginally lower |
When a financial services firm, a fintech startup, or a family office decides to set up in the UAE, two names dominate every conversation: DIFC and ADGM. Both zones offer English common law, independent courts, and world-class financial regulators. Both attract serious international capital. The question is not which is better in absolute terms; it is which is better for your specific business, your clients, and your long-term plans. This guide gives you the full picture so you can make that call with confidence.
If you are also looking at the broader UAE free zone landscape, the Dubai free zone business setup guide at diac.ae covers more than 40 zones across all sectors.
DIFC vs ADGM: What They Have in Common (and Where They Differ)
What DIFC and ADGM Share
It is worth establishing the baseline before focusing on differences. Both zones were designed to attract global financial institutions and are genuinely world-class, not just by UAE standards.
- Independent legal systems based on English common law
- Dedicated courts with internationally enforceable judgements
- 100% foreign ownership with zero requirement for a UAE national partner
- Zero corporate tax on qualifying income (within the zone)
- Zero income tax on employees and founders
- Full repatriation of profits and capital
- USD-denominated commercial environment
- Recognised by the IOSCO multilateral memorandum of understanding
Where They Differ
The differences come down to location, regulator culture, ecosystem maturity, and specific legal capabilities. DIFC is in Dubai, connected to the Dubai International Financial Centre gate complex and the DIFC Courts. ADGM is on Al Maryah Island in Abu Dhabi, adjacent to some of the world’s largest sovereign wealth funds. That geography difference is not trivial: it shapes your client access, your network, and your day-to-day operating environment.
Legal Framework: DIFC Courts vs ADGM Courts
DIFC Courts
The DIFC Courts are one of the most established international commercial courts in the world. They operate in English, apply English common law principles adapted for the DIFC context, and have mutual recognition arrangements with courts in the UK, Singapore, Australia, and many other common law jurisdictions. Judgements from the DIFC Courts can be enforced through Dubai onshore courts, which is a significant practical advantage. The DIFC Courts also handle disputes between DIFC entities and mainland UAE parties under their Conduit Jurisdiction, which is unique and enormously useful for businesses that operate across the zone boundary.
- Full suite of civil and commercial jurisdiction
- Conduit Jurisdiction for cross-boundary enforcement
- Established case law library from 2004 onwards
- Judges drawn from the UK, Australia, Singapore, and Hong Kong
ADGM Courts
The ADGM Courts are newer but built to an equally high standard. They also apply English common law and are staffed by judges from the same pool of international legal talent. Where ADGM has a specific edge is in its foundations and trusts framework. The ADGM Foundations Regulations are widely considered more detailed and more flexible than the DIFC equivalent, which makes Abu Dhabi the jurisdiction of choice for family offices setting up foundations for wealth structuring and succession planning.
- English common law applied from first principles
- ADGM Foundations Regulations: leading framework for family office trusts
- Close alignment with Abu Dhabi Global Market’s wealth management sector
- Growing case law, with strong appellate structure
If your business involves a UAE foundation or holding structure for family wealth, ADGM deserves serious consideration for its legal edge on that specific question. For general financial services, both courts are equally credible.
Regulatory: DFSA (DIFC) vs FSRA (ADGM); Which Is Better?
DFSA: Dubai Financial Services Authority
The DFSA has regulated DIFC since its launch in 2004. It is one of the most recognised financial regulators in the Middle East and is an IOSCO signatory. If you are licensing a fund manager, a brokerage, a payment institution, or a wealth management firm, DFSA authorisation carries significant weight with international counterparties and correspondent banks. The DFSA also operates the FinTech Hive, which is the region’s largest fintech accelerator and provides a path to a restricted licence for early-stage companies.
- Licensing categories: fund management, broker-dealer, banking, insurance, payment services, investment advisory
- FinTech Hive accelerator for early-stage financial tech companies
- Recognised by the UK FCA and other tier-one regulators
- Strong enforcement record, which adds credibility to licence holders
FSRA: Financial Services Regulatory Authority
The FSRA regulates ADGM and has built a strong reputation since ADGM’s launch in 2015. It is also an IOSCO signatory and covers the same range of regulated activities as the DFSA. Where FSRA stands out is in its RegLab innovation sandbox, which gives fintech companies a time-limited regulatory environment to test products with real customers before applying for a full licence. This is particularly useful for payment technology, digital asset, and robo-advisory startups that need live market data before committing to a full regulatory application.
- RegLab sandbox: test live products under regulatory supervision
- Digital asset framework: one of the UAE’s clearest licensing paths for crypto and tokenised assets
- Wealth management: close proximity to Abu Dhabi sovereign wealth ecosystem
- Insurance: ADGM-regulated captive insurance is a growing sector
Verdict: For a fintech company that wants to test before committing to full regulatory capital requirements, FSRA’s RegLab gives ADGM a practical edge. For a firm that needs the strongest possible brand signal to international institutional counterparties, DFSA and DIFC’s twenty-year track record carries more immediate weight.
Business Activities: What Each Zone Specialises In
DIFC Specialisations
DIFC has spent two decades building a deep, interconnected financial ecosystem. The breadth of institutions and professionals in one place creates a genuine network effect.
- Asset management and fund administration
- Capital markets and securities trading
- Private equity and venture capital
- Insurance and reinsurance
- Islamic finance and Sharia-compliant products
- Professional services (law firms, audit, accounting) serving financial institutions
- Fintech, payment technology, and digital banking
ADGM Specialisations
ADGM has developed strong verticals that align with Abu Dhabi’s own strategic priorities.
- Family office and private wealth management
- Foundations and trusts for succession and estate planning
- Sovereign wealth and institutional asset management
- Digital assets and virtual asset services
- RegTech and fintech sandbox incubation
- Commodities trading and natural resource finance
For UAE holding company structures that sit above operating businesses across multiple countries, both DIFC and ADGM are legitimate choices. The selection often comes down to where the founders and management team are based and where the primary banking relationships sit.
Cost: DIFC vs ADGM Formation and Annual Fees
Both zones are premium-priced compared to general free zones like IFZA or RAKEZ. That said, for a regulated financial firm, the licensing cost is a fraction of the total cost of compliance, so the difference between DIFC and ADGM should not be the primary decision driver.
| Cost Item | DIFC (USD approx.) | ADGM (USD approx.) |
| Registration fee | 8,000 – 10,000 | 7,000 – 9,000 |
| Regulatory licence fee | Varies by activity | Varies by activity |
| Data protection fee | Included | Included |
| Office (flexi / shared desk) | From USD 6,000/yr | From USD 5,000/yr |
| Annual renewal | Similar to registration | Similar to registration |
| Typical first-year total (non-regulated) | USD 12,000 – 18,000 | USD 10,000 – 16,000 |
| Typical first-year total (regulated) | USD 30,000+ | USD 25,000+ |
Costs above are estimates based on non-regulated SPV / holding company or regulated financial service licence setups. Exact figures depend on activity type, office choice, regulatory capital requirements, and whether a physical office or a flexi-desk is taken. DIAC provides free, detailed cost modelling before any engagement begins.
Location: Dubai Financial Centre vs Al Maryah Island Abu Dhabi
DIFC Location Advantage
The DIFC precinct in central Dubai occupies a unique position physically and commercially. It sits between Downtown Dubai and the Dubai International Airport corridor, with direct access to DIFC Metro station and walking distance to major five-star hotels, law firms, and the Dubai Court. The FinTech Hive and Gate Avenue create a campus feel that makes it easy to meet investors, clients, and regulators informally. For firms that want to be at the centre of the most active deal-making city in the Middle East, DIFC’s location is hard to beat.
ADGM Location Advantage
ADGM’s position on Al Maryah Island places it within walking distance of the Abu Dhabi Global Market Square and adjacent to major Abu Dhabi banks, sovereign wealth entities, and government institutions. For asset managers and wealth firms that want direct access to Abu Dhabi Investment Authority (ADIA), Mubadala, and other major institutional allocators, being in Abu Dhabi is not just a convenience; it is a relationship advantage. The island is also rapidly developing as a luxury commercial and residential hub, with high-quality office stock and easy access to Abu Dhabi International Airport.
Neither location is better in absolute terms. Dubai is the more international and transactional city. Abu Dhabi is where the deepest pools of government and sovereign capital sit. Your choice should follow your primary client relationships and where your partners and management want to live. DIAC’s team at diac.ae regularly advises on this question as part of a broader UAE market entry assessment.
Which to Choose: Financial Services Decision Guide
Here is a practical decision framework based on business type. This should not replace professional advice, but it will help you go into that conversation with a clearer sense of direction.
| Business Type | Recommended Zone | Key Reason |
| Fund manager / hedge fund | DIFC | Deepest institutional LP network |
| Family office (wealth structuring) | ADGM | Foundations framework advantage |
| Fintech (testing stage) | ADGM | RegLab sandbox for live testing |
| Fintech (scaling, institutional) | DIFC | DFSA brand signal, FinTech Hive network |
| Payment institution | Either / both | Depends on client base geography |
| Asset management (regional) | DIFC | 20+ years of ecosystem depth |
| Digital asset / crypto firm | ADGM | Clear FSRA virtual asset framework |
| Private equity / VC | DIFC | Ecosystem, deal flow, co-investment access |
| Holding company (Abu Dhabi) | ADGM | Abu Dhabi relationship proximity |
| Holding company (Dubai / global) | DIFC | Central location, broad treaty network |
| Insurance / reinsurance | DIFC | Established insurance market depth |
| Captive insurance | ADGM | ADGM-specific captive regulations |
Can You Have Both?
Yes. A number of international firms operate a DIFC entity alongside an ADGM entity to access both regulatory environments and both geographic markets. This is more common for larger institutions. Startups and early-stage firms typically pick one, prove the model, and expand later. Both DIFC and ADGM entities can be held under a UAE holding company, a UAE foundation structure, or an international parent.
| Useful Links
External: DIFC Official Website | DFSA – Dubai Financial Services Authority External: ADGM Official Website | FSRA – Financial Services Regulatory Authority Related: Dubai Free Zone Business Setup Related: UAE Holding Company Setup | UAE Foundation Setup Related: Dubai Business Setup Services |
FAQs: DIFC vs ADGM
Is DIFC or ADGM better for a fintech startup?
It depends on stage. ADGM’s RegLab sandbox is ideal for early-stage fintech companies that want to test a product with real customers under regulatory supervision before committing to a full licence. DIFC’s FinTech Hive accelerator and deeper institutional network make it the stronger choice for fintech firms at the scaling stage. For guidance on which route suits your product and team, a DIAC consultation can map the right path.
Do DIFC and ADGM operate under the same legal system?
Both zones apply English common law independently, but they are separate legal jurisdictions with their own courts, regulations, and case law. A contract governed by DIFC law is not automatically enforceable in ADGM courts, and vice versa. Both sets of courts are internationally respected, but you must choose your governing law at the contract drafting stage.
What is the minimum capital requirement for a DIFC or ADGM financial licence?
Minimum capital requirements vary by licence category and regulator. For unregulated holding companies or SPVs, there is typically no minimum paid-up capital requirement. For regulated activities such as fund management, brokerage, or banking, both DFSA and FSRA impose category-specific minimum capital that can range from USD 10,000 for restricted licences to millions for banking authorisations. Your specific requirements should be confirmed with a licensed UAE financial advisory firm.
Can a DIFC or ADGM company do business on the UAE mainland?
Free zone entities, including DIFC and ADGM companies, generally cannot conduct business directly with UAE mainland clients without a mainland branch or commercial agency arrangement. However, financial services regulated by DFSA or FSRA can serve both UAE and international clients within the scope of their licence. For firms that need both free zone and mainland reach, a mainland company formation in Dubai can be paired with a DIFC or ADGM entity as part of a dual-structure strategy.
Is ADGM or DIFC better for a family office?
ADGM is widely considered the stronger jurisdiction for family office structures, particularly when foundations or trusts are involved. Its ADGM Foundations Regulations provide more detailed and flexible wealth planning tools than DIFC’s equivalent framework. For a single-family office or multi-family office serving UHNW clients, ADGM’s proximity to Abu Dhabi sovereign capital and its specific legal provisions make it the preferred choice. See the UAE foundation setup guide for more detail on UAE foundation structures.
How long does it take to set up in DIFC or ADGM?
For a non-regulated entity (holding company, SPV, family office without regulated activity), setup in both zones typically takes four to six weeks from submission of complete documentation. For a regulated financial services licence, the timeline extends to three to six months depending on licence category, the quality of the application, and the regulator’s current caseload. Having an experienced UAE business setup adviser handle the application significantly reduces back-and-forth with the regulator.
Which zone has lower fees, DIFC or ADGM?
ADGM is generally marginally lower in registration fees, particularly for non-regulated entities. For regulated financial licences, the difference narrows because regulatory capital requirements and compliance costs are a far larger proportion of total cost than registration fees. Neither zone is cheap by UAE free zone standards, and both are premium-priced relative to non-financial zones like IFZA or RAKEZ. The decision should not hinge on cost alone.
| Not sure whether DIFC or ADGM is the right fit?
DIAC consultants specialise in UAE financial free zone setup for fintech, asset management, family offices, and holding companies. Book a free call and get a personalised recommendation. |
| About the Author
Adil Ahmad is a UAE business setup consultant at DIAC with deep expertise in financial free zone formation, regulatory licensing, and corporate structuring across DIFC, ADGM, and the UAE mainland. He advises fintech founders, family offices, and asset managers on jurisdiction selection, regulator engagement, and entity structuring. |